However, the economic value of a patent developed by a company does not usually appear directly on its balance sheet.
A patent purchased from another company may be recorded as an asset, but its recorded amount does not necessarily show its true business value.
The Limits of Financial Statements
Financial statements are like a company’s medical chart.
One of the key statements, the balance sheet, shows where the company’s money comes from and what kinds of assets have been acquired or built using that money. The balance sheet is divided into two sides: the right-hand side shows how funds were raised, and the left-hand side lists the assets obtained.
No one knows exactly when financial statements were first created or who invented them, but they were already widely used in Venice during the Middle Ages. In Japan, they were formally introduced in the Meiji era.
The fact that financial statements have been used for centuries is proof of how effective this system is.
However, in today’s information-driven economy, the shortcomings of financial statements are becoming more and more apparent.
In particular, financial statements alone do not fully show the value of intangible assets such as patents, know-how, and brands.
Intangible Assets Are Information Assets
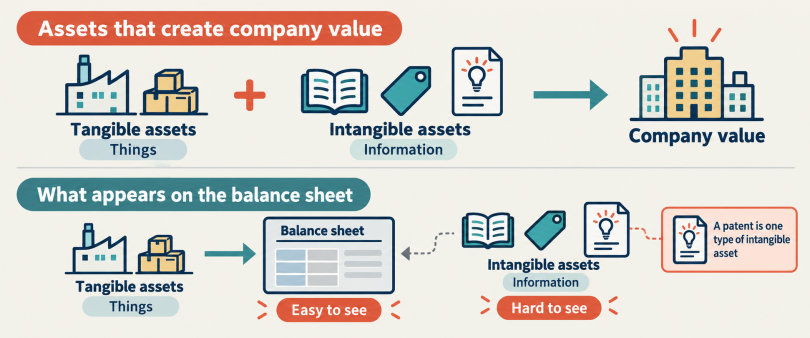
Financial statements are good at recording assets that are easy to identify and value, such as land, factories, inventory, and securities. A company that owns many such assets is often seen as wealthy.
It’s not impossible to record intangible things as assets, but intangibles are vague and hard to measure in value, so they are rarely included. As a result, financial statements end up focusing on tangible assets.
Intangible assets include know-how (experience), sales information, manuals, human networks, brands (corporate image), and so on. Patents are also a typical intangible asset.
In other words, intangible assets can be described as valuable information assets used in business activities.
Many people recognize that intangible assets are the real source of a company’s earnings power and competitiveness. But clearly identifying what intangible assets a company has, and putting into words how much they are worth, is extremely difficult.
Patent Costs Are Visible, but Patent Value Is Not
Today, it is often said that most corporate assets are intangible.
Many mergers and acquisitions (M&A) are carried out to obtain the intangible assets of the target company. When an acquiring company pays more than the book value of the target’s assets, the explanation is that there are intangible assets not shown on the financial statements.
There may therefore be a large gap between the corporate value shown by financial statements and the company’s true value, including its intangible assets.
The economic value of a patent created through a company’s own research and development is not normally recorded directly as an asset at that value.
Obtaining a patent costs money. Research and development also require substantial investment. However, even if a company spends one million yen and obtains a patent that later produces one billion yen in value, it cannot simply record “a patent worth one billion yen” on its balance sheet.
The accounting treatment may be different when a company purchases a patent from another company. A purchased patent may be recorded as an intangible asset based on its acquisition cost. For example, if Company A buys Patent P from Company B for 300 million yen, Company A may record Patent P as an asset based on that purchase price.
However, outsiders still cannot know whether Patent P is really worth 300 million yen as a business asset. The amount recorded in the financial statements is not necessarily the same as the patent’s true economic value.
Because the economic value of an internally developed patent is not fully shown in financial statements, it is difficult to make everyone understand that value. In many cases, the people who best understand the value of a patent are those who use it—or those who may be prevented from doing business because of it.
On the other hand, the cost of obtaining and maintaining patents is easy to see. If their value is not clearly explained, patents may look like nothing more than costs.
The value of a patent is also not determined only by the money spent to obtain it. It depends greatly on the scope of the patent rights and on how effectively those rights protect the company’s business.
This is similar to money itself: if you have never used money, you may not fully understand what it can do. Patents are similar in that way.
Are Japanese Companies Undervalued?
One common stock market indicator is PBR, or Price-to-Book Ratio.
PBR shows how the market price of a company’s shares compares with its book value per share. In simple terms, it compares the net assets recorded in the company’s financial statements with the value given to the company by the stock market.
When a company has valuable patents, know-how, brands, and other intangible assets, its balance sheet alone may not fully explain its potential value.
Yet many Japanese companies have a PBR below 1.0. This means that the stock market values them at less than the net assets recorded on their balance sheets. In theory, such companies may appear to be significantly undervalued.
Investor relations, or IR, means communicating information about a company’s management, financial condition, and business performance to investors. One purpose of IR is to provide information that financial statements alone cannot show. This can increase investor confidence and may reduce the company’s cost of raising capital.
If a company can clearly explain the quality and quantity of its patents and other intangible assets, investors may better understand its potential and true corporate value. Its share price may even rise as a result.
Useful intellectual property management begins with identifying the intangible assets a company owns and explaining how those assets create earnings and competitive strength. Patents should not be treated only as costs. Companies should also explain what their patents protect and how they support the business.